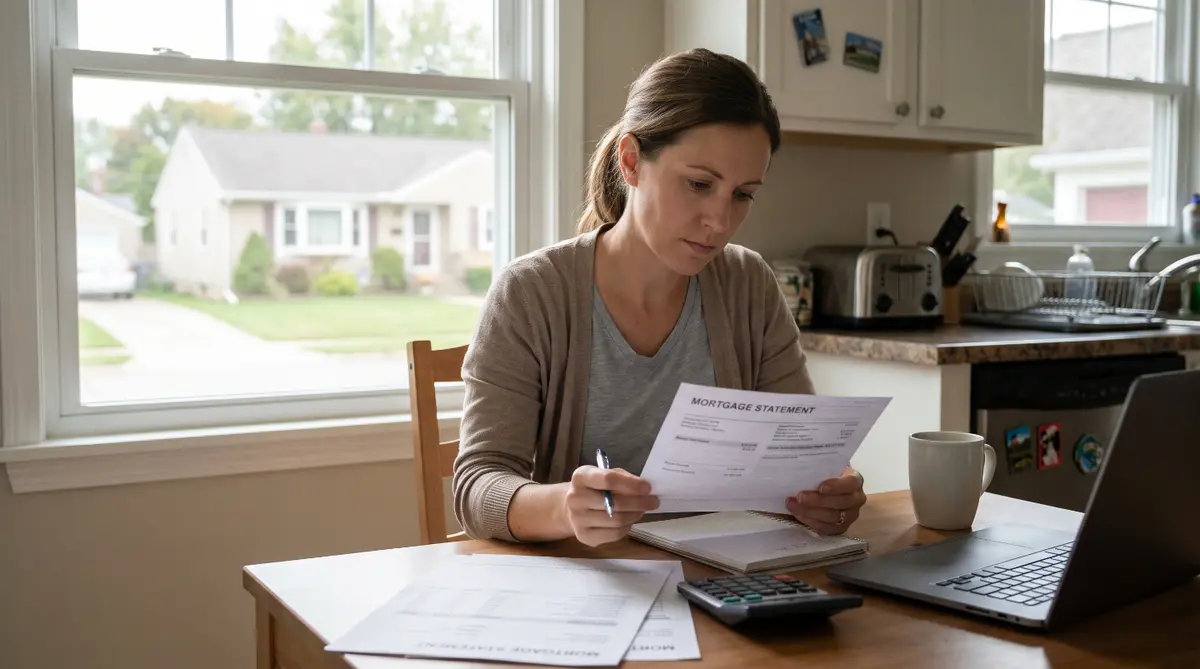
American homeowners could eventually pay less for mortgage insurance and certain refinancing expenses under a new federal housing order. But the potential savings will depend on eligibility rules and how quickly the changes are implemented.
President Donald Trump signed the executive order, titled Decreasing Housing Costs for the American People, on October 22, 2026. It directs federal housing officials to pursue changes involving mortgage insurance, refinancing costs, certain government home loans, and manufactured housing.
What Changes Under the New Order?
One major provision directs the Federal Housing Finance Agency (FHFA) to establish a pilot program that would identify eligible borrowers whose home equity meets the requirements for mortgage insurance cancellation.
The program would use automated property valuations and other available information to assess whether borrowers qualify. Mortgage servicers would also be directed to notify eligible homeowners when cancellation may be possible, subject to applicable laws and operational requirements.
The order also directs the FHFA to consider expanding an existing title-insurance waiver pilot into an ongoing nationwide program for eligible mortgage refinances.
The goal is to reduce certain closing costs by allowing approved alternatives to traditional lender’s title insurance.
How Much Could Mortgage Insurance Savings Add Up To?
The potential savings can be easier to understand through a simple example.
Consider a homeowner paying $150 each month in mortgage insurance.
That expense adds up to $1,800 over 12 months.
If the homeowner eventually qualifies for cancellation and the payment ends, that money could remain in the household budget instead of going toward insurance premiums.
However, this is an illustrative calculation, not a government estimate of typical savings. Actual premiums vary, and the order does not establish that every homeowner paying mortgage insurance will qualify.
The Detail Existing Borrowers Should Not Miss
The new mortgage-insurance pilot is intended to cover mortgages made after the program is established. That limitation means homeowners with existing loans should not assume they will automatically receive the same treatment.
The program must also account for equity requirements, payment history, contractual obligations, and other applicable eligibility rules.
Homeowners with existing private mortgage insurance should review their current loan documents and contact their mortgage servicer to understand the cancellation options already available under their loan terms.
Could Refinancing Become Cheaper?
Potentially, for eligible borrowers.
The order directs the FHFA to consider broader use of alternatives to title insurance and other measures that could reduce expenses on qualifying refinances. It also requires cost savings from the title-assessment program to be passed on to borrowers and disclosed to them.
But lower closing costs alone do not guarantee that refinancing is worthwhile. Borrowers still need to compare interest rates, total fees, monthly payments, and how long they expect to keep the loan.
The order separately directs the Agriculture and Veterans Affairs departments to reduce interest rates on certain single-family loans they make directly. It does not establish a universal rate reduction for every USDA or VA-related mortgage.
What Homeowners Should Watch Next
The practical impact will depend on the FHFA’s implementation decisions, the eligibility criteria, and the timing of the new programs.
For now, the most important distinction is between a policy designed to reduce future housing expenses and savings a particular household can actually claim.
The order creates a path toward lower costs for some borrowers. The next step is determining which homeowners qualify, when the changes take effect, and how much they ultimately save.
Sedha Patel is a personal finance strategist with over 5 years of experience analyzing consumer banking trends, liquidity management, and wealth preservation. With a professional background in accounting and corporate finance, Sedha specializes in translating macro monetary policy into practical money moves for everyday savers. When not dissecting market data, Sedha researches fixed-income allocation models and tax-advantaged investing strategies.